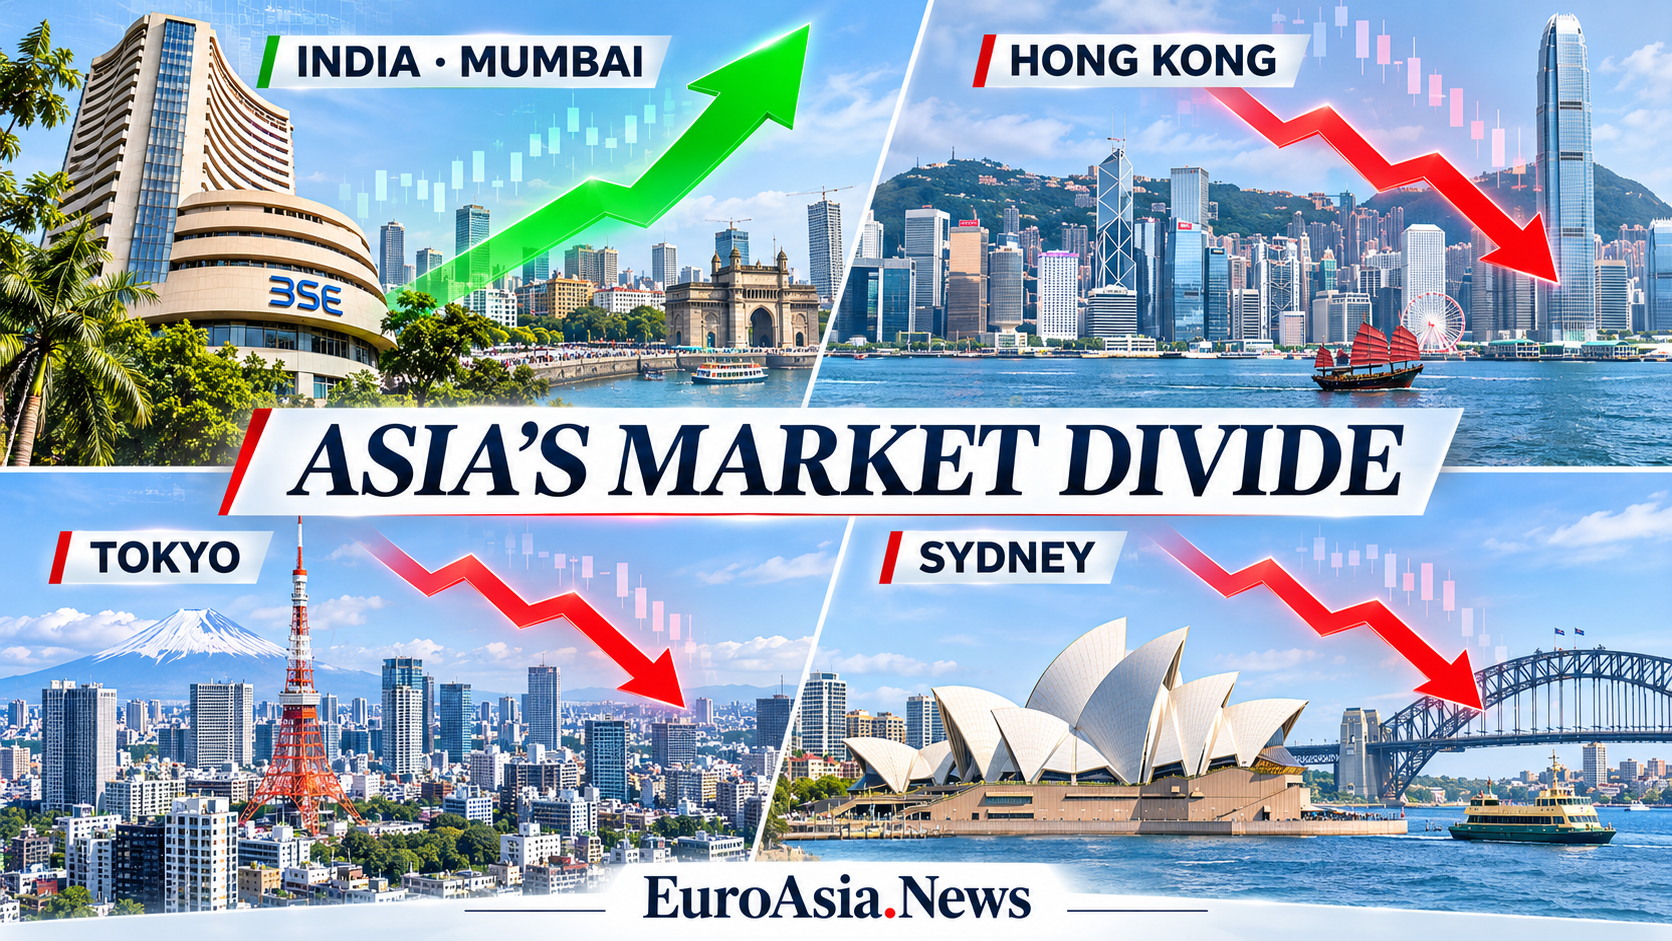
South Korea briefly suspended trading after an 8% plunge, Japanese chipmakers suffered heavy losses, while Hong Kong and Sydney proved more resilient. India moved in the opposite direction: its main indexes recovered from an opening decline as investors bought software and banking shares.
The contrast reveals a market increasingly divided by exposure to the artificial-intelligence investment boom. Manufacturers supplying chips and equipment faced sharp selling; economies benefiting from cheaper oil and investment moving away from AI showed greater resistance.
The Kospi fell more than 8% in early trading, triggering a 20-minute circuit-breaker suspension. Bloomberg reported an intraday decline reaching 8.8%, with Samsung Electronics and SK Hynix initially losing more than 9%. Those were early-session figures, rather than closing results.
“South Korea: chip dependence magnifies the shock Seoul experienced the most dramatic disruption.”
EuroAsia.News, reporting from Hong Kong
Selling subsequently eased. At 2pm Korean time, the Kospi stood at 5,118.73, down 4.91%—still a severe decline, but substantially above its morning low. Foreign investors were selling more than ₩1 trillion of shares, according to Seoul Economic Daily. Seoul
Samsung and SK Hynix supply memory essential to advanced computing. Their vulnerability illustrates how concern about American data-centre construction can rapidly affect Asian manufacturers: fewer or delayed projects could weaken expectations for equipment orders and memory demand.
Tokyo: the equipment suppliers take the hit
Japan’s Nikkei 225 closed 6.0% lower at 57,434.77, its biggest percentage fall since April 2025. That translated into a loss of roughly 3,640 points in one session.
An earlier market snapshot showed SoftBank Group down 10.4%, memory-chip producer Kioxia 10.8%, Tokyo Electron 5.4% and Advantest 4.6%. These readings were taken before the final close. SoftBank represents investment exposure to AI, while Tokyo Electron and Advantest supply equipment used in semiconductor production and testing. Selling therefore reached several stages of the computing supply chain.
Hong Kong: a retreat after Thursday’s surge
Hong Kong’s decline was much smaller. The Hang Seng was down approximately 1%, while mainland China’s Shanghai Composite fell around 1.2% in the same reported snapshot. Nevertheless, China’s STAR Market and ChiNext AI index both lost more than 4%, showing greater pressure beneath the broad benchmarks.
The reversal followed Thursday’s 3.7% Hang Seng rally, when Alibaba, Tencent, Xiaomi and Meituan advanced. Investors were reassessing a strong preceding session rather than experiencing losses comparable with Seoul’s trading halt.
Sydney: a smaller decline, different exposure
Australia’s S&P/ASX 200 was reported around 0.5% lower at 9,020.80, a much gentler fall than Tokyo’s.
Thursday had brought a 2.6% gain, supported by miners including BHP, Rio Tinto and Fortescue as metals strengthened. Energy producers Woodside and Santos moved lower as oil weakened. These different commodity exposures help explain why an American chip-stock shock does not affect every Australian heavyweight equally.
India: software shares provide a counterweight
India initially opened lower, but at 10.33am Indian time, the Nifty 50 had risen 0.51% to 24,662.80, while the Sensex gained 0.76% to 79,917.60. Foreign investors had bought approximately ₹150 billion—$1.6 billion—of Indian equities on Thursday, while lower oil prices supported sentiment.
Software companies were early winners: Infosys rose 2.01%, Tech Mahindra 1.34%, TCS 1.30% and HCL Technologies 1.26% shortly after opening. Those figures preceded the broader indexes’ recovery.
Friday’s divide was therefore more precise than “Asia crashes”. Markets heavily exposed to AI hardware suffered most; India’s software-led technology sector offered a counterweight. The next question is whether this remains a rotation between sectors—or develops into a broader retreat from equities.